This special analysis on Currency Correlations was originally published in September 2026’s issue of Foreign Exchange Consensus Forecasts. The unabridged article and a recent sample issue are available to industry professionals. Simply send us an email at editors@consensuseconomics.com
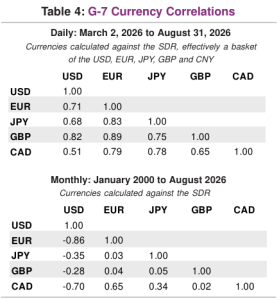
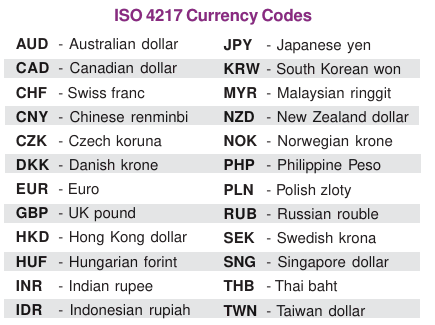
Our Method: Currency Correlation AnalysisHistorical relationships between currencies can provide useful guidelines for both users of currency projections and those examining hedging or risk management strategies. The following study uses correlation analysis to examine some of the linkages between various currencies. The calculations were made using daily data over the period from March 2, 2026 to August 31, 2026 (Tables 1, 3 and 4). To provide a longer term historical perspective, we have also calculated correlations using monthly data (end month points) for the period from January 2000 through August 2026 (Tables 2 and 4). The correlation coefficients shown in the tables indicate the degree to which two exchange rates tend to move together, with positive values of close to one (+1.00) indicating that such currency pairs move very closely together and values nearer minus one (-1.00) indicating that the two currencies generally move in opposite directions. Values close to zero show that there is little or no relationship between the two currencies concerned. For the sake of simplicity we have calculated correlations for the European and Asian currencies against the US dollar (USD), while correlations between the G-7 currencies (including the USD) were compared by using exchange rates against the Special Drawing Right (SDR), which is effectively a basket of the USD, EUR, JPY, GBP and CNY, (which was included in 2016). ISO 4217 codes for the currency identification symbols used in the tables are explained in the box at the bottom of page 35. |
|||
 |
|||
Western and Eastern Europe – Strong Positive Currency Correlations
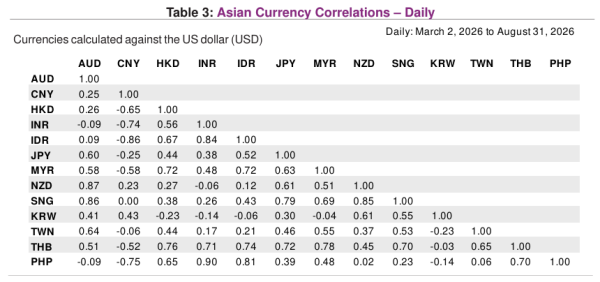
Asia – Strong Negative Currency Correlations for Oil Importing EconomiesForeign exchange markets in Asia have also been particularly volatile during the US-Iran war, reflecting the region’s large number of open, export-oriented economies and its exposure to global trade and energy flows. This is evident in India, Indonesia and the Philippines, where currencies have weakened in tandem and prompted central banks to intervene in support of domestic markets. Japan has been a notable exception. Unusually large intervention in the yen by US and Japanese authorities has distorted its historical relationships with other Asian currencies, although its correlation with the Malaysian ringgit has remained comparatively positive (Table 3 above). In contrast, despite efforts by the PBoC to limit the pace of appreciation, relatively low inflation and China’s large current account surplus have continued to exert upward pressure on the renminbi, making it move in the opposite direction to much of the region. Elsewhere, the Australian and New Zealand dollars remain highly positively correlated.
|
|||
| DOWNLOAD A RECENT COPY OF FOREIGN EXCHANGE CONSENSUS FORECASTS | |||
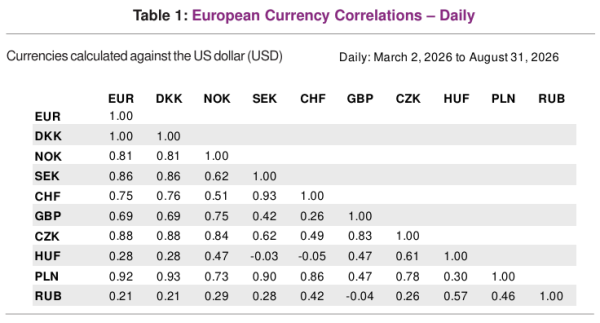
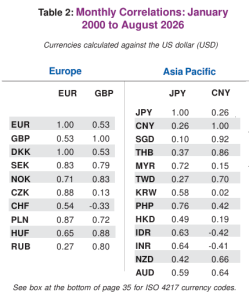 The US-Iran war has pushed energy prices higher and contributed to a surge in global bond yields, with volatility spilling over to foreign exchange markets. Risk sentiment has fluctuated considerably, with risk sensitive and emerging market currencies moving increasingly in tandem with geo-political headlines. Currencies of economies with high energy import dependency have been especially vulnerable as rising import costs have weakened trade balances and added to inflation pressures. This is especially relevant for the euro, as its diversification away from Russian energy in recent years has left it more exposed to global energy markets, international competition for supply and external price shocks. Similarly, the Czech koruna, Polish zloty and Swedish koruna are similarly exposed to the global energy shock, helping to explain their high correlation with both the euro and one another (Table 1). Hungary has been the notable exception. Although the economy is highly reliant on imported Russian oil, the forint has instead been heavily influenced by domestic political factors following the April 12 general election. This has considerably reduced its correlation with the euro and other European currencies relative to historical patterns (Table 2). The Russian rouble has also behaved differently from its regional peers. While higher energy prices have improved Russia’s terms of trade, international sanctions and Ukrainian drone strikes have contributed to supply disruptions and delays in the settlement of energy exports. These market frictions have distorted the transmission of both geopolitical news and energy price movements into the currency.