In addition to their regular forecasts, once a year we survey our panellists in Latin American Consensus Forecasts (in August) and Eastern Europe Consensus Forecasts (in July) for their projections for growth in a range of economic sectors, based on conventional GDP output breakdowns used in the individual countries.
| Latin American Consensus Forecasts | Eastern Europe Consensus Forecasts | ||
|---|---|---|---|
| Argentina | Venezuela | Czech Republic | Estonia |
| Brazil | Colombia | Hungary | Latvia |
| Chile | Peru | Poland | Lithuania |
| Mexico | Russia | Romania | |
| Turkey | Slovakia | ||
| Bulgaria | Slovenia | ||
| Croatia | Ukraine | ||
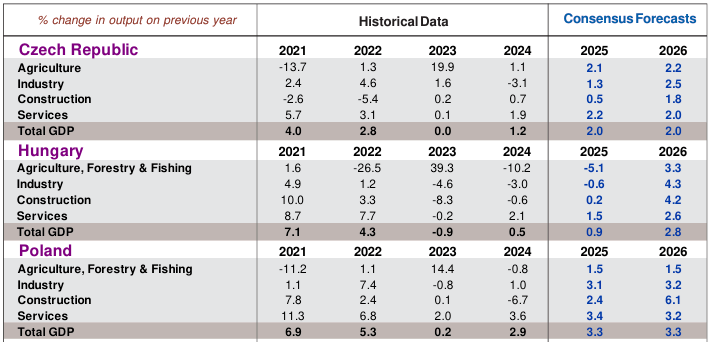
The table below shows a sample of the data from our Eastern Europe survey on Sectoral Growth (in this case, from our July 2025 Eastern Europe Consensus Forecasts survey).
Production Challenges
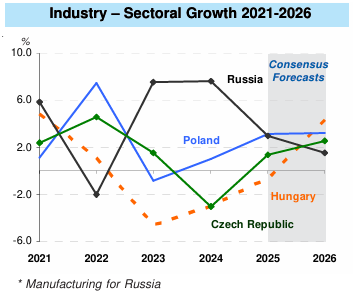 Structural and political issues within the euro zone continue to hinder industrial performance across Central and Eastern Europe (CEE). Output has been notably weak in Hungary, largely reflecting its substantial reliance on the automotive, electronics, and general manufacturing sectors. Updated forecasts indicate that Germany – the economic powerhouse of Europe – will begin to gain traction in 2026 and beyond, driven primarily by anticipated increases in public expenditure and a relaxation of fiscal policy. Its success will depend on the effective implementation of structural reforms and the its adaptability of the economy to the electric vehicle transition amid intensifying competition from China. For CEE countries, nearshoring production and shortening supply chains for Western Europe offer substantial opportunities. Provided that CEE effectively embraces and integrates advanced technologies, it stands to benefit from a regionalisation of output and revival in Western Europe.
A portion of text from Eastern Europe Consensus Forecasts, July 21, 2025.